Litong Zhang张历潼

Marshall School of Business, University of Southern California

Phone (+1) 919-599-1901
Email litong.zhang@marshall.usc.edu
701 Exposition Blvd., Ste. 231, Los Angeles, CA 90089

Welcome! I am a sixth-year Ph.D. candidate in Finance and Business Economics at the University of Southern California. I study social finance and behavioral finance, with a focus on how investor communication, memory, and cognitive reference points shape trading behavior and asset prices. My work combines large-scale text data and LLM-supervised measurement with empirical asset pricing. I am on the 2026–2027 job market.

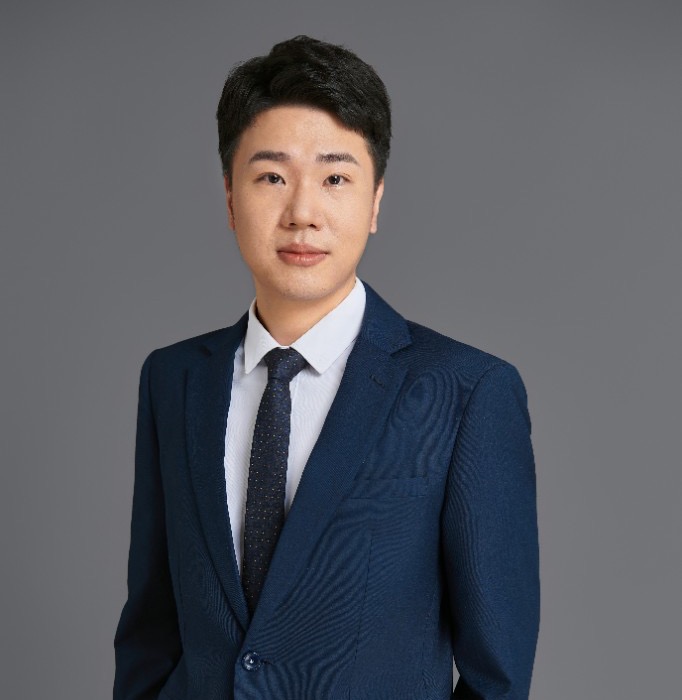
Portrait of Litong Zhang

01  /  Education

Education

University of Southern California

Ph.D. in Finance and Business Economics

2021 – 2027 (expected) — Marshall School of Business

Duke University

M.A. in Economics

2019 – 2021

University of Utah

B.S. in Finance and Mathematics

2014 – 2018

02  /  Research

Research

Job Market Paper

Reference-Dependent Sentiment

Litong Zhang. Sole authored.

Abstract

Under what circumstances is a given paper gain/loss more relevant to trading decisions? I examine whether reference-dependent thinking among investors is associated with the strength of disposition-effect trading. Using 185.1 million StockTwits posts from 2013 to 2024 and an LLM-supervised classification, I construct a daily measure of reference-dependent sentiment, capturing whether investors frame their positions as gains or losses relative to past prices. In the cross-section, talking about gains (losses) is associated with more (less) retail selling of stocks with embedded gains (losses). At the market level, when investors talk more about gains (losses), turnover is higher (lower) on up-market (down-market) days. Around earnings announcements, buying good-news stocks after investors have been talking about gains and selling bad-news stocks after they have been talking about losses earns a Fama-French five-factor alpha of 1.03% per month, or 12.4% annualized, while the reverse strategy does not. Exploiting the introduction of StockTwits’ leaderboard as a plausible shock to framing legitimacy, I find that public reinforcement of gain-loss framing strengthens the relationship between reference-dependent sentiment and trading. Overall, reference-dependent sentiment identifies when the disposition effect shows up more strongly in trading and in prices around earnings news.

PDF

Working Papers

Reference-Point Fluency and Memorability

Litong Zhang. Sole authored.

Abstract

This paper investigates how cognitive accessibility of reference-points shapes investor behavior, focusing on the disposition effect: the tendency to sell winning investments while holding losing ones. I show that round numbers serve as fluent and memorable cognitive reference points that amplify the disposition effect. The gain-loss gap in selling is 6.20 percentage points for regular-price positions and 8.60 percentage points for round-price positions, an amplification of 2.40 percentage points (about 39 percent of the regular-price baseline); in account-level regressions the round-versus-regular amplification remains about 1.2 to 2.0 percentage points, or roughly one-third of the baseline disposition effect on regular-price holdings. A stock-split design that rescales purchase bases after the trade addresses purchase-time selection: the amplification persists when the adjusted basis remains round and vanishes when the split breaks roundness. Complementary evidence from earnings announcements shows that round consensus forecasts similarly organize market attention. The results highlight that reference dependence depends not only on what the reference point is, but on how easily it can be processed and remembered.

Draft coming soon.

Working in Progress

Reference-Dependent Sentiment and Price Dynamics

Litong Zhang. Sole authored.

Abstract

How does reference-dependent sentiment predict the path of stock prices? I examine whether investors’ discussion of gains and losses predicts returns at different horizons. Using an LLM-supervised classification of StockTwits posts, I measure the daily intensity of reference-dependent sentiment in the market. When investors talk more about gains, subsequent prices fall in the short run, consistent with gain realization creating selling pressure. The effect weakens at intermediate horizons, and prices reverse upward at longer horizons. This pattern is consistent with temporary selling pressure that is gradually absorbed as the market clears, with limits to arbitrage potentially delaying price adjustment. Overall, the evidence suggests that reference-dependent sentiment helps predict not only whether investors trade, but also the timing of price pressure and its reversal.

Social Gathering and Amplified Familiarity Bias

Litong Zhang. Sole authored.

Abstract

This paper investigates the causal role of contemporaneous social interaction in mutual fund managers’ portfolio choices. Using manually collected information on the Top 30 MBA networks of alumni reunion cohorts, I show that mutual fund managers connected to senior officers (CEO, CFO, and Chairman) at firms increase connected holdings following the MBA alumni reunions. Stock-level performance tests show that fund managers do not achieve significant positive returns on these connected positions after reunion events, favoring the familiarity hypothesis: an increase in contacts leads to a notable surge in buying behavior despite the absence of superior returns. These findings highlight the role of social networks as channels for the formation of behavioral bias.

03  /  Teaching

Teaching

University of Southern California

ECON 351: Microeconomics for Business

Sole Instructor, Undergraduate Core | Fall 2024

GSBA 602: Selected Issues in Economic Theory I

Teaching Assistant for Prof. Anthony Marino, Ph.D. Core | Fall 2023

GSBA 612: Selected Issues in Economic Theory II

Teaching Assistant for Prof. Odilon Câmara, Ph.D. Core | Spring 2024